Menu
Call
Contact
Blog

I Was a Passenger in a Car Accident in California: Who Do I Sue?

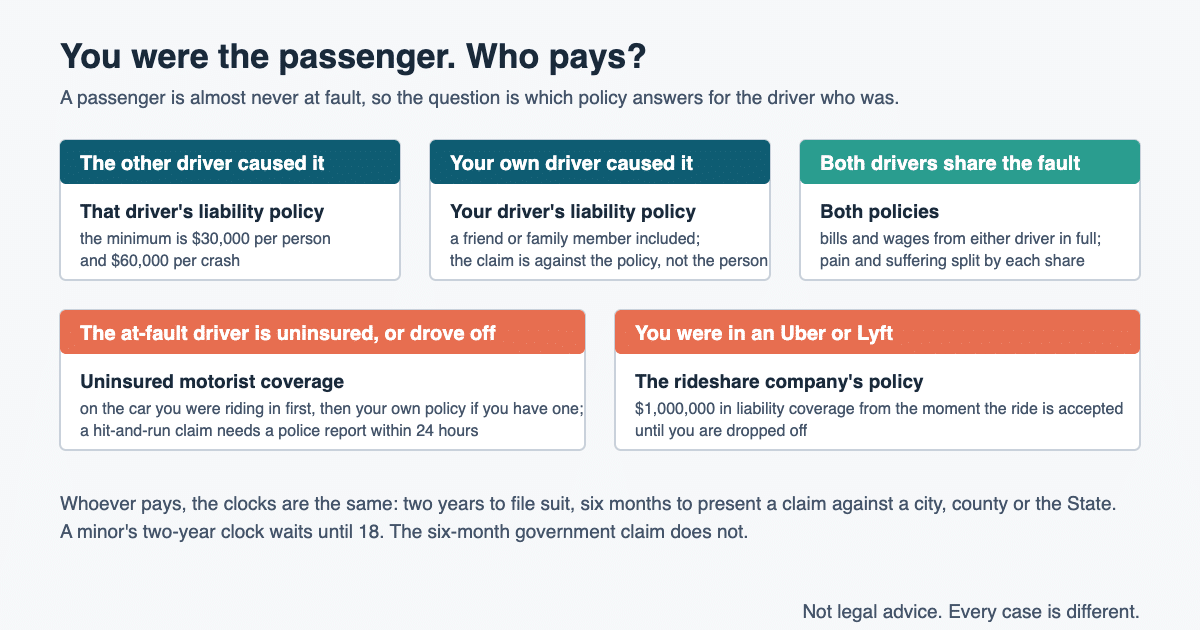
Grid of passenger car accident scenarios in California and which insurance policy pays in each: the other driver's liability policy, your own driver's liability policy, both policies when fault is shared, your own uninsured and underinsured motorist coverage, and the rideshare company's policy

Reviewed by David Gammill, California trial attorney · Last reviewed: October 20, 2026

If you were a passenger in a car accident in California, you can make a claim against every driver whose negligence caused the crash: the other driver, the driver of the car you were in, or both, each through that driver’s auto liability insurance. If a driver had no insurance or not enough, your own uninsured and underinsured motorist coverage can pay, even though you were not driving. A passenger is almost never at fault, which makes the liability part of the claim the easy part. The hard parts are finding every policy that applies and getting past the feeling that a claim against your friend’s insurance is a lawsuit against your friend. It is not, and this guide explains why, scenario by scenario.

The Bottom Line

  • You claim against the negligent driver’s insurance, whoever that driver was: the other car, your own driver, or both when both share fault.
  • The money comes from the insurer: a claim against your friend’s policy is paid by the insurance company your friend has been paying premiums to for exactly this.
  • Two at-fault drivers means two policies: California lets a passenger collect economic damages in full from either negligent driver, while each pays non-economic damages only in proportion to fault.
  • Your own policy may matter: uninsured and underinsured motorist coverage follows you into other people’s cars, and medical payments coverage can pay bills regardless of fault.
  • Rideshare passengers are the most heavily covered: from the moment a ride is accepted until you are dropped off, the rideshare company must carry $1,000,000 in liability coverage.

If you were hurt as a passenger and do not know which insurer to call, call 310-750-4149 first. The consultation is free, and sorting the policies is the first thing we do.

Grid of passenger car accident scenarios in California and which insurance policy pays in each: the other driver's liability policy, your own driver's liability policy, both policies when fault is shared, your own uninsured and underinsured motorist coverage, and the rideshare company's policy

Who Pays a Passenger’s Claim?

Whoever was at fault, through that driver’s insurer, and sometimes more than one. You are not suing anyone in most cases; you are presenting an insurance claim against a driver’s liability policy, and the lawsuit is the backup if the insurer refuses to pay what the injury is worth. The list of candidates is short, and the facts of the crash decide which of them are in it:

  • The other driver, if that driver caused the crash: claim against their liability policy.
  • Your own driver, if your driver caused it: claim against your driver’s liability policy.
  • Both drivers, if both were negligent: claims against both policies.
  • Your own auto insurer, if an at-fault driver was uninsured, underinsured, or fled: your uninsured and underinsured motorist coverage, plus medical payments coverage if you carry it.
  • A company, if the at-fault driver was working: the employer’s commercial policy, or for Uber and Lyft, the rideshare company’s required coverage.
  • A public entity, if a city, county, or state vehicle or a road defect caused the crash: a written government claim first, on a six-month clock.

What If the Other Driver Caused the Crash?

The simplest case: your claim is against the other driver’s bodily injury coverage, and your own driver’s insurer is involved only for the car. Your medical bills, your lost wages, and your pain and suffering are all pursued against the at-fault driver’s policy, in the same way any injured person’s claim would be. The ceiling is that driver’s policy limit. California requires only $30,000 per person and $60,000 per accident for bodily injury, with $15,000 for property damage, for policies issued or renewed on or after January 1, 2025 (Vehicle Code § 16451), and the $60,000 is shared by everyone hurt in the crash, which can include the driver of your car. When several people were injured by a minimum-limits driver, the per-accident cap is the first problem to solve, and the answer is usually your own underinsured motorist coverage, covered below.

What If My Own Driver Caused the Crash?

Your claim is against your driver’s liability insurance, and the driver’s bank account is not involved. This is the scenario people avoid, because the driver is a friend, a spouse, a parent, or a coworker, and a claim feels like an accusation. Separate the two. Liability insurance exists so that when the person who caused an injury cannot afford to pay for it, the insurer does. Your driver has been paying for that coverage; a claim against it is what the premiums were for. The driver’s role is small: a statement to the insurer, and, if a lawsuit becomes necessary, a name on the caption, which is a formality the insurer’s lawyer handles. The settlement is paid by the insurance company.

Two complications are worth knowing before you call. First, some policies contain a household or family exclusion that limits or removes coverage when the injured passenger is a relative who lives with the driver. Whether such a clause applies to your claim depends on the policy’s wording and the facts, and it is a question for a lawyer rather than for the adjuster who will cite it. Second, if the driver’s limits are not enough, the law allows a claim against the driver personally for the rest, but pursuing a friend’s savings is rarely worth the cost to either of you, and your own underinsured motorist coverage is usually the practical route.

What If Both Drivers Were at Fault?

You claim against both, and California’s rules make that a good position for a passenger. California compares fault and assigns each driver a percentage. For a driver, that percentage reduces what the driver can recover. For a passenger who did nothing wrong, it decides who pays what. Under Civil Code § 1431.2, your economic damages, the medical bills, the lost wages, and the other losses with a receipt, can be collected in full from any defendant found at fault, so a 20 percent driver with a large policy can be made to pay the whole of your bills and then sort out the rest with the other driver. Your non-economic damages, the pain, the suffering, and the loss of what you could do before, are different: each driver pays only its own percentage of those. A 70/30 split means the 70 percent driver’s insurer pays 70 percent of your pain and suffering, and the 30 percent driver’s insurer pays 30 percent.

The practical consequence is that a passenger in a two-driver crash should never settle with one insurer without knowing what the other will pay, and should never sign a release that is broader than the driver it names. Our guide to how a California car accident settlement is calculated explains the two categories of damages and why the split matters.

What If a Driver Was Uninsured or Underinsured?

Your own auto policy steps in, even though you were a passenger in someone else’s car. Three coverages matter, and each follows you rather than the vehicle:

  • Uninsured motorist coverage pays when the at-fault driver had no insurance, up to your policy’s limit. It applies whether you were driving, riding, or walking.
  • Underinsured motorist coverage pays the gap when the at-fault driver’s limit is smaller than your injury, up to your own limit, after the other policy has paid out.
  • Medical payments coverage, where you carry it, pays medical bills regardless of fault, quickly, and without a liability fight.

If the at-fault driver fled, the claim is an uninsured motorist claim with conditions: the injury must have come from physical contact with the other vehicle, the crash must have been reported to the police within 24 hours, and a sworn statement must be filed with your insurer within 30 days after that (Insurance Code § 11580.2). The 24-hour report is the one passengers miss while they are in the emergency room; have someone make it for you. Our hit-and-run accident page covers that route.

If you have no auto policy of your own, you may still be covered as a resident relative under a parent’s or spouse’s policy, and the driver’s own policy may carry uninsured motorist coverage that extends to passengers. Your health insurance pays the medical bills in the meantime, and the claim reimburses it later. A lawyer’s first task on a passenger case is to read every policy in the household and in the car.

What If I Was in an Uber or Lyft?

From the moment a ride is accepted until you are dropped off, the rideshare company must carry $1,000,000 in liability coverage, and it applies to you whichever driver caused the crash. California’s rideshare insurance statute sets that requirement, and it also requires uninsured and underinsured motorist coverage of $60,000 per person and $300,000 per incident from the time a passenger enters the vehicle until the passenger exits, as the company’s own obligation. That is usually far more coverage than either personal auto policy in the crash would have provided. If the rideshare driver caused the crash, the claim runs against the company’s policy; if another driver did, that driver’s policy is first and the rideshare coverage backs it up. Our Uber and Lyft accident page explains the three coverage periods and why the app status at the moment of the crash decides which applies.

What If I Was in a Company Vehicle or Hit by One?

The employer is usually liable with the driver, and the employer’s policy is usually larger. When a driver causes a crash while doing their job, California holds the employer responsible for the employee’s negligence, a rule called respondeat superior, and the claim can be made against the company’s commercial policy as well as the driver. A delivery van, a work truck, a company car, or a bus brings that second defendant into the case, and with it a corporate adjuster and a policy that may be many times the personal minimum. Our truck accident page explains how the company’s records are obtained and used.

If the vehicle you were in belonged to a city, a county, the State, or a transit agency, or a road defect caused the crash, the defendant is a public entity and a written claim must be presented to it within six months, before any lawsuit, explained in our guide to the six-month government claim deadline. That clock is not paused for a passenger who is a minor.

What If the Passenger Is a Child?

A parent or guardian brings the claim, the lawsuit clock waits, and the settlement needs a judge’s approval. For a claim against a private driver, the two-year deadline does not run while the injured person is under 18 (Code of Civil Procedure § 352), so a child has until two years after turning 18 to file. The six-month government claim deadline is the exception: that section does not apply to claims against public entities, and a child’s claim against a city or a school district runs on the adult clock. Any settlement of a minor’s injury claim is submitted to the court for approval, which protects the child by checking the amount and controlling how the money is held until adulthood. A parent can pursue the claim; a parent cannot sign it away.

What Can a Passenger Recover?

The same damages as any injured person, with no fault reduction. Medical expenses past and future, lost wages and lost earning capacity, out-of-pocket costs, and the non-economic damages: pain, suffering, emotional distress, loss of enjoyment of life, and loss of consortium for a spouse. Because a passenger’s fault share is almost always zero, the valuation turns entirely on the injury and the available coverage, and the coverage search above is where the number is made or lost. Our guide to how long a California car accident settlement takes explains the stages, and the deadline to file a lawsuit against a driver is two years from the crash, explained in our guide to Code of Civil Procedure § 335.1.

What Should an Injured Passenger Do First?

Six things, in this order.

  1. Get medical care the same day. The chart is the proof of the injury, and a gap at the start is the insurer’s first argument.
  2. Get both drivers’ insurance information, not only the other car’s. You may have claims against both.
  3. Photograph the scene, the cars, and your injuries, and write down what happened that night.
  4. Give no recorded statement to any liability insurer, including your own driver’s. Passengers are asked for statements because they are the witness both sides want; give yours to your own lawyer.
  5. Notify your own auto insurer, even though you were not driving, so your uninsured, underinsured, and medical payments coverages are preserved; if the driver fled, make the 24-hour police report.
  6. Talk to a lawyer before you sign anything. A release naming “all parties” closes the claim against the driver you have not yet made it against.

Our guide to what to do after a car accident that was not your fault covers the first days in more detail.

Will a Claim Against My Friend’s Insurance Hurt Our Friendship?

Usually not, once the friend understands who pays. The claim is paid by the insurer, out of the coverage the friend bought for this situation. The friend’s premium may or may not change; whether a driver is treated as at fault for rating purposes is governed by California’s insurance regulations and by what the crash was, not by whether you made a claim. What helps: tell the friend directly that the claim is against the policy, not against them; let your lawyer handle every communication with the insurer so the friend is never in the middle; and remember that declining to make the claim does not help the friend, it only leaves your medical bills with you while the insurer keeps the premium.

Frequently Asked Questions

Can I sue my friend if I was a passenger in their car?

You can, and in practice you present a claim against your friend’s liability insurance and the insurer pays it. A lawsuit is filed only if the insurer will not pay what the injury is worth, and the insurer defends and pays it then too.

Can a passenger be found at fault?

Rarely. A passenger who grabbed the wheel, who knowingly got into a car with a driver who was obviously drunk, or who was not wearing a seat belt may face a comparative-fault argument that reduces the recovery. Knowingly riding with a drunk driver is the argument insurers reach for most; our drunk driver accident victim page explains how those cases run. None of those arguments bars the claim.

Can I file against more than one driver?

Yes, against every driver whose negligence contributed. Economic damages can be collected in full from any one of them; non-economic damages are split by percentage of fault.

What if my driver and the other driver blame each other?

That is their dispute, not yours. You present a claim against both policies and let the insurers argue percentages with each other. A passenger is the witness both sides want, which is why neither should get a recorded statement.

How long do I have to make a passenger claim in California?

Two years from the crash to file a lawsuit against a driver, paused while an injured child is under 18; six months to present a written claim when a public entity is responsible, with no pause for a child; and for a hit-and-run uninsured motorist claim, a police report within 24 hours and a sworn statement within 30 days after it.

Do I need a lawyer for a passenger claim?

If the injury was minor, one driver was clearly at fault, and that driver has enough coverage, perhaps not. If more than one policy may apply, if any driver was uninsured, if a rideshare or company vehicle was involved, or if your driver is someone you love, a free consultation is worth the call, because the value of a passenger claim is mostly the coverage search. Our guides to whether a minor car accident needs a lawyer and choosing a California personal injury lawyer cover the decision.

Whatever path your claim takes, download our free guide, Crash Course: A California Car Accident Guide (2026), to keep every deadline and first step in one place.

Related Pages

Our Torrance car accident attorney page explains how the firm handles a crash case from the first call through trial, including the coverage search and the deadlines, for Torrance and the South Bay.

About Gammill Law

David Gammill is a former Los Angeles County Deputy District Attorney who has tried over 100 cases to verdict, first as a prosecutor and then as a trial lawyer for injured people. Every case is different, and past results do not guarantee a similar outcome. Gammill Law Accident & Injury Lawyers represents people in personal injury, wrongful death, and civil rights cases across California, and its attorneys bring more than 40 years of combined legal experience to every case they take. The firm has recovered more than $100 million for California clients across verdicts and settlements. Its results include a $21.1 million wrongful death verdict, a $16 million school sexual abuse verdict, and a $12 million whistleblower retaliation verdict; every case is different, and prior results do not guarantee a similar outcome. You can read more on our case results page. Consultations are free, there is no fee unless the firm recovers, and the firm takes calls in English and Spanish. Call 310-750-4149 or request a free case evaluation.

If you were hurt riding in someone else’s car and the insurers are already pointing at each other, call 310-750-4149. We will tell you which policies apply and keep your friend out of the middle.

This page is attorney advertising and general information, not legal advice for any specific situation. Deadlines and outcomes are fact-specific; consult a licensed California attorney about your own circumstances. Prior results do not guarantee a similar outcome.

David Gammill, California trial lawyer and founder of Gammill Law

My name is David Gammill. I am a California trial lawyer and the founder of Gammill Law Accident & Injury Lawyers. Our firm has recovered more than $100 million for California clients. Our results include a $21.1 million wrongful death verdict, a $16 million school sexual abuse verdict, and a $12 million whistleblower retaliation verdict. I learned to try cases in front of juries early in my career as a Deputy District Attorney, and trying cases remains the backbone of my practice.
Ask Gammill AI Calculator